Every fall, our neighbor Walt does the same thing with the thick envelope from his Medicare plan. He sets it on top of the refrigerator, right next to the church bulletin and the coupons he means to use, and says, "Nothing's broken, Bob. Why fix it?"
Last January, something was broken. The pharmacy two blocks from his house had left his plan's network, and one of his heart medicines had moved to a pricier tier. Every bit of it was spelled out in that envelope. Walt just never opened it, and he spent the next twelve months paying for a decision he never actually made.
Well, folks, Walt is a smart man. He ran a hardware store for thirty years. His problem wasn't brains. It was assuming this year's plan would stay the same next year. Plans change every single year, and Medicare open enrollment is your once-a-year chance to catch those changes before they catch you.
When is Medicare open enrollment for 2027 coverage?
This year's window runs October 15 through December 7, 2026. Whatever you pick during those weeks starts on January 1, 2027. You'll hear it called "open enrollment" and "the annual enrollment period." Same thing. Medicare.gov lists exactly what you can change during the window.
Here's that calendar in words. By September 30, your Medicare Advantage or Part D plan mails you a letter called the Annual Notice of Change. In early October, next year's plans show up on Medicare's free Plan Finder. The window opens October 15, your plan must receive any change by December 7, and new coverage starts January 1.
What should I check before I decide?
Start with Walt's envelope. The Annual Notice of Change lists exactly what your plan is changing for 2027: premiums, deductibles, which drugs it covers, and which doctors and pharmacies are in its network. Read it with a pen in your hand.
Then check these five things against your real life, not the brochure:
In plain words: confirm your doctors are still in the network, make sure every medicine is covered at the dose you actually take, check that your usual pharmacy is still preferred, compare the total yearly cost instead of just the monthly premium, and only count the extra benefits you would really use.
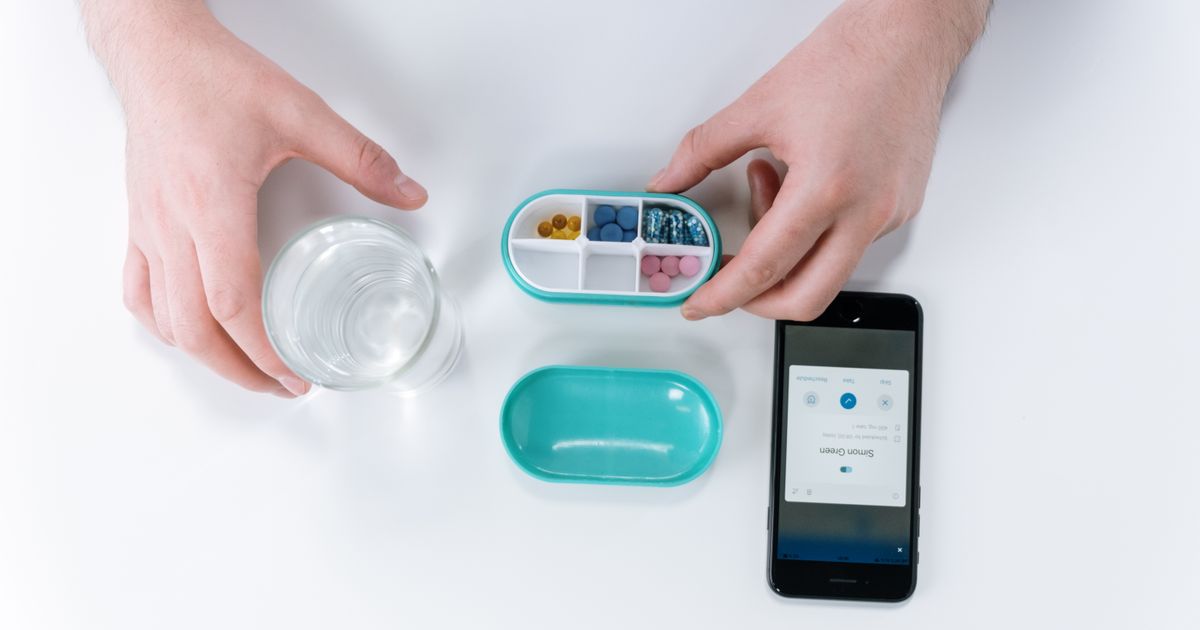
For the medicines, Medicare's Plan Finder lets you type in your exact drugs and pharmacy and see an estimated cost for the whole year. Have your pill bottles on the table when you do it. Guessing at a dose is how people end up surprised in February.
What's different about drug costs in 2027?
There's a yearly ceiling on what you pay for covered prescriptions under Part D. For 2027, Medicare set that ceiling at $2,400, up from $2,100 in 2026. The standard deductible goes up too, to $700, though your own plan's deductible may be lower.
The cap helps a lot if you take expensive medicines. If you don't, the deductible and your copays matter more. That's one more reason to run your own numbers instead of trusting last year's.
If one medicine still costs too much, ask your pharmacist to compare your plan's price with a coupon price. Our guide on how to use GoodRx at the pharmacy shows how. Just know that coupon purchases don't count toward your plan's yearly cap.
Who can help me compare plans for free?
Here's the thing most folks don't know. Every state has a free, unbiased Medicare counseling program called SHIP. These counselors don't sell insurance and don't earn a commission. You can find yours at shiphelp.org or by calling 1-800-MEDICARE. Book early. Appointments fill up fast once October gets going.
You'll also see more ads and get more phone calls than usual this fall. Medicare itself won't call you out of the blue to sell you a plan, so treat any caller like that with caution. Our guide on how to spot a phone scam walks through what to do.
What Walt did differently this year
This year, Walt opened the envelope in September. He found out his plan is dropping a specialist he likes, so he called and booked a free SHIP appointment for October 20. He's bringing his pill bottles. The whole thing took him twenty minutes.
You don't have to switch plans every year, folks. Staying put is a perfectly good choice when you've checked the facts. What we don't want is for you to stay put because the envelope never got opened.
So tell us in the comments: have you opened your Annual Notice of Change yet? What surprised you in it?